
How Older Adults and Families Can Recognize, Avoid and Respond to Today's Scams
Last Updated: August 2026
A Greater Lansing senior safety resource for older adults, adult children and families.
Scams are nothing new, but the way scammers reach us — and how convincing they can be — has changed dramatically.
I see it myself.
Calls claiming I missed jury duty. Emails that appear to come from Amazon or Apple. Messages warning that an account has been compromised. Fake invoices. Suspicious text messages. Computer security warnings. Someone claiming there is an urgent problem that needs to be handled immediately.
I receive some version of these regularly, and even when you know what to look for, some of them can appear remarkably convincing.
That concerns me because I work with many older adults and families throughout Greater Lansing. If those of us who routinely stop and verify these messages are receiving them, imagine how many are reaching someone who is living alone, recently lost a spouse, is managing unfamiliar financial responsibilities, or simply hasn't encountered that particular scam before.
The goal of this resource isn't to make anyone afraid to answer the telephone, use email, shop online or manage their finances.
It's to help you recognize when something doesn't feel right — and know what to do next.
Today's Scams Can Fool Almost Anyone
One of the biggest mistakes we can make is assuming only people who aren't familiar with technology fall for scams.
Today's scammers can be sophisticated.
They may know your name. They may know where you live. An email may contain a familiar company logo. A caller may appear to be calling from a legitimate telephone number. A text may look like a real fraud alert from your bank. Someone may claim to be from Amazon, Apple, Social Security, law enforcement or another organization you recognize.
And increasingly, scammers don't begin by asking you for money.
They begin by telling you they are trying to protect you.
They might say:
- Someone purchased an expensive item using your Amazon account.
- Your Apple account or computer has been compromised.
- Suspicious activity has been detected in your bank account.
- You missed jury duty and could be arrested.
- Your Social Security number has been connected to criminal activity.
- A family member is in trouble and needs immediate help.
- Your money isn't safe and needs to be moved to another account.
The details change, but the strategy is remarkably consistent:
Create fear. Create urgency. Keep you engaged. Prevent you from checking with someone else. Then get you to provide information, give them access, or move money.
The Numbers Are Sobering
Fraud affects people of every age, but the potential financial consequences for older adults can be particularly serious.
The Federal Trade Commission reports that older adults reported losing more than $3 billion to fraud in 2025. The FTC has also documented a significant increase in older adults reporting very large losses to scammers impersonating trusted businesses and government agencies.
These aren't always small losses involving a gift card or a few hundred dollars. Some victims have lost tens of thousands of dollars — and in extreme cases, substantial portions of their retirement savings.
That makes scam awareness more than a technology issue.
It's a family, financial and senior-transition issue.
Mike's 60-Second Scam Rule
If you receive an unexpected call, email, text message or computer warning asking you to take immediate action: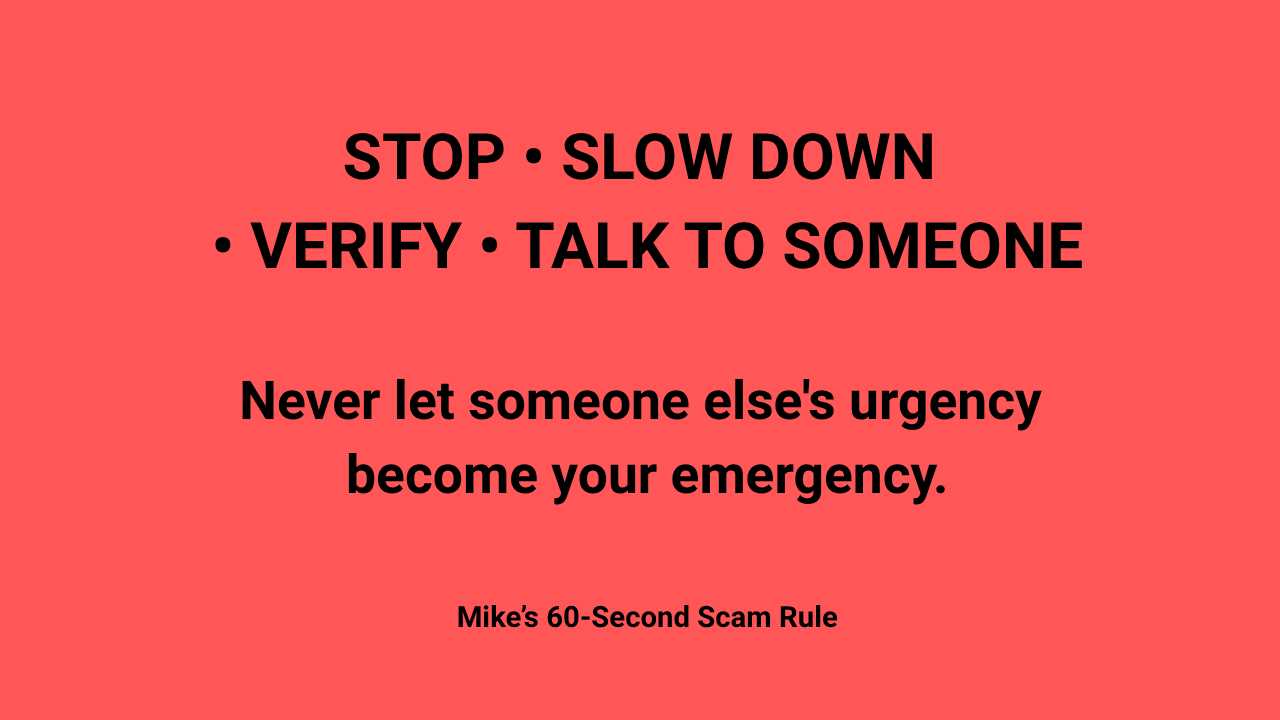
STOP
Don't send money. Don't click the link. Don't call the telephone number contained in the message. Don't provide a verification code. Don't allow someone remote access to your computer.
SLOW IT DOWN
Scammers want you to act before you have time to think.
Statements such as "you must act immediately," "don't hang up," "don't tell anyone," or "your money is at risk" should be warning signs.
VERIFY INDEPENDENTLY
Hang up.
If the caller claims to represent your bank, call the telephone number printed on the back of your bank or credit card.
If it's supposedly Amazon or Apple, go directly to the company's app or website yourself.
If someone claims to represent a government agency, court or law-enforcement organization, independently locate the agency's official telephone number and call it.
Never use the telephone number, link or contact information supplied by the person you're trying to verify.
TALK TO SOMEONE YOU TRUST
Before sending money, moving money or providing sensitive information because of an unexpected contact, talk with someone you trust.
That might be an adult child, family member, friend, banker, attorney, financial advisor or another trusted professional.
Sometimes another person asking just one question can stop a scam before any damage is done.
When something doesn't feel right, stopping for a few minutes may be the most important thing you can do.
Jury Duty, Police & Government Impersonation Scams
One of the more alarming scams making the rounds involves a telephone call claiming that you missed jury duty, failed to respond to a court notice, or now have a warrant for your arrest.
The caller may claim to be from the sheriff's department, local police, a court, the IRS, Social Security, Medicare or another government agency.
What makes these calls particularly convincing is the amount of information the caller may already have. They might know your name, address or other personal information. Caller ID may even appear to show the name or telephone number of a legitimate government agency.
Then comes the pressure.
The caller may tell you that you need to pay a fine immediately to avoid arrest. You might be instructed to remain on the telephone while withdrawing money, purchasing gift cards, transferring funds, using a payment app or depositing money into a cryptocurrency ATM.
Some scammers even create fake government websites or documents to make their story appear legitimate.
Warning Signs
Be suspicious when someone claiming to represent a court, police department or government agency:
-
Threatens immediate arrest if you hang up.
-
Demands immediate payment.
-
Tells you to purchase gift cards or use cryptocurrency.
-
Requests payment through a wire transfer or payment app.
-
Tells you not to speak with family members, your bank or anyone else.
-
Insists that you remain on the telephone while obtaining the money.
-
Asks for personal or financial information you weren't expecting to provide.
What Should You Do?
Hang up.
Do not debate the caller, and don't rely on the telephone number appearing on Caller ID.
If you're concerned that the call could be legitimate, independently locate the telephone number for the court, sheriff's department, police department or government agency and call them yourself.
Do not call a telephone number supplied by the person who contacted you.
The Federal Trade Commission warns that government agencies will not call unexpectedly and demand money or personal information, and legitimate agencies will not demand payment through gift cards, cryptocurrency or similar methods.
Remember Mike's 60-Second Scam Rule: Stop. Slow Down. Verify. Talk to Someone.
A legitimate organization will give you the opportunity to verify what you're being told.
Amazon, Apple & Retail Account Scams
You've probably seen one of these.
An unexpected email, telephone call or text says something like:
"Your Amazon account has been charged $1,499."
"Your Apple ID has been compromised."
"Your subscription has been renewed."
"An order is being shipped that you didn't authorize."
The natural reaction is to think, I didn't buy that.
That's exactly the reaction the scammer wants.
The message usually provides a telephone number or link to dispute the charge. But when you call that number or click the link, you're contacting the scammer — not Amazon, Apple or the company named in the message.
The Scam May Start With a Fake Purchase — But That's Not the Real Objective
Once you respond, the scammer may claim that your account has been compromised and offer to help.
You may be asked to:
-
Provide your account password.
-
Give them a security or verification code sent to your phone.
-
Provide credit-card or banking information.
-
Install software so they can remotely access your computer.
-
Sign into your bank account while they are connected to your computer.
-
Transfer money to a supposedly "safe" account.
-
Purchase gift cards or use cryptocurrency to correct the problem.
At that point, what began as a fake Amazon purchase can become a much more serious financial fraud.
Don't Use the Contact Information in the Message
This is one of the most important habits you can develop.
If you receive an unexpected Amazon, Apple or other retail-account warning:
Don't click the link.
Don't call the telephone number in the message.
Instead, independently open the company's app or type the website address you normally use into your browser. Check your actual account for orders, charges or security notifications.
You can also independently contact the company using contact information obtained from its official website.
What If There Really Is an Unauthorized Charge?
Check the account directly.
Then check your credit-card or bank account independently.
If you see a transaction you don't recognize, call the telephone number printed on the back of your credit or debit card.
That lets you initiate the conversation with an organization you know, rather than trusting someone who unexpectedly contacted you.
Be Especially Careful With Verification Codes
A legitimate security code sent to your telephone or email is intended for you.
If someone unexpectedly calls and asks you to read a verification code back to them, stop.
That code may be the final piece the scammer needs to access your account or reset your password.
Never provide an unexpected caller with a security or verification code.
A Simple Question Can Help
When an unexpected message says something is wrong with an account, ask yourself:
"How can I verify this without using anything this person just gave me?"
Then stop the conversation and verify it independently.
Stop. Slow Down. Verify. Talk to Someone.
Bank & Credit Card Fraud Department Impersonation Scams
Some of the most convincing scams begin with someone who appears to be trying to protect your money.
You receive a telephone call or text message supposedly from your bank or credit-card company:
"Did you authorize this $2,400 purchase?"
"We've detected suspicious activity on your account."
"Someone is attempting to transfer money from your account."
"Your debit card has been compromised."
You know you didn't make the transaction, so you respond.
That's when the real scam begins.
Why These Scams Can Be So Convincing
The caller may already know your name, telephone number or even the name of your financial institution.
Caller ID can also be manipulated, or "spoofed," so the call appears to come from a familiar telephone number or organization.
The scammer may sound professional and reassuring. There may even be background sounds that make the call seem like it is coming from a busy customer-service or fraud department.
Instead of threatening you, the person may say:
"Don't worry. I'm going to help you secure your account."
That reassurance can make this type of scam particularly dangerous.
Never Move Money to "Protect" Your Money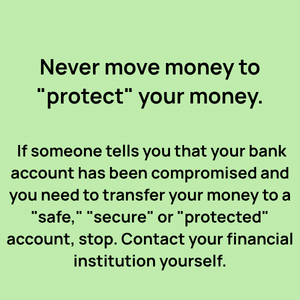
A scammer may tell you that your bank account is no longer safe.
You may be instructed to transfer money to another account, withdraw cash, purchase cryptocurrency, use a payment app or move your savings into a supposedly secure or protected account.
Stop immediately.
A legitimate bank will not unexpectedly call and instruct you to move your money to a special account in order to protect it from fraud.
The "safe account" belongs to the scammer.
Don't Trust Caller ID Alone
Seeing your bank's name on Caller ID does not prove that your bank is calling.
If someone contacts you unexpectedly about suspicious activity:
Hang up.
Then call the telephone number printed on the back of your debit or credit card, use your bank's official mobile app, or independently contact your local bank.
If there really is a problem, your bank will be able to tell you.
Never Share Security Codes
Your bank may send a one-time security or verification code when someone attempts to access your account.
That code is for you.
A scammer may tell you:
"I'm sending you a verification code. Please read it back to me so I can confirm your identity."
Don't do it.
The scammer may actually be attempting to sign into your account, change your password or authorize a transaction.
Never provide an unexpected caller with a password, PIN or security verification code.
When in Doubt, End the Conversation
You don't need to determine whether the caller is telling the truth while you're still on the telephone.
Hang up and verify the situation yourself.
A legitimate financial institution won't object to you protecting yourself by independently calling back.
Your money doesn't become safer because someone pressures you to move it quickly.
Computer & Tech-Support Scams
You're working on your computer when suddenly a warning fills the screen.
It may say:
"Your computer has been infected."
"Windows Security Alert."
"Your Apple device has been compromised."
"Do not turn off your computer."
"Call immediately for technical support."
Some warnings include flashing graphics, loud sounds, countdowns or repeated messages designed to make it appear that something serious is happening.
A telephone number is conveniently displayed for you to call.
Don't call it.
The warning itself may be the scam.
The Goal Is to Get Access to Your Computer
Once you call, the supposed technician may tell you that your computer, internet connection or financial accounts have been compromised.
They may ask you to install remote-access software so they can "diagnose" or "repair" the problem.
That can give a stranger access to your computer.
Depending upon the access you provide, a scammer may be able to view files, watch what you're doing, obtain passwords or convince you to sign into financial accounts while they are connected.
Never Give an Unexpected Caller Remote Access
If someone unexpectedly contacts you claiming to be from Microsoft, Apple, your internet provider, your bank or another company and asks for remote access to your computer:
Stop.
Don't install software at their direction.
Don't give them control of your screen.
And don't sign into your bank, investment or credit-card accounts while someone you don't know has remote access to your computer.
A Computer Warning Can Turn Into a Banking Scam
One particularly dangerous version of the tech-support scam doesn't end with the computer.
The supposed technician may claim that hackers have accessed your bank account.
You may then be transferred to another person who claims to work for your bank, a government agency or a fraud department.
That person may tell you that your savings are in immediate danger and must be moved.
Now several people may appear to be confirming the same story.
They're working together.
The computer problem, the bank representative and the government official may all be part of the same scam.
What Should You Do With a Suspicious Pop-Up?
Don't call the telephone number displayed in the warning.
Don't click buttons within the pop-up simply because they say "Close," "Cancel" or "Remove Virus."
If possible, close the browser or application normally. If you cannot close it, shut down or restart the computer.
If you're still concerned, contact someone you trust or a reputable computer professional using contact information you obtain independently.
What If You Already Allowed Someone Into Your Computer?
Disconnect the computer from the internet and end the remote session.
If you provided financial information or signed into financial accounts while the person had access, contact your bank or financial institution immediately using a telephone number you independently verify.
Change potentially compromised passwords from a different, trusted device and consider having the computer inspected before using it again for sensitive financial activity.
Don't be embarrassed about asking for help.
The sooner you act, the better the opportunity may be to limit additional damage.
One Rule Worth Remembering
Microsoft, Apple, your bank or another legitimate organization doesn't need you to give an unexpected stranger control of your computer in order to protect you from an unsolicited warning.
When a computer message creates panic and tells you to call immediately:
Stop. Slow Down. Verify. Talk to Someone.
Grandchild & Family Emergency Scams
The telephone rings.
A frightened voice says:
"Grandma, I need your help."
There has been an accident. An arrest. A medical emergency. A problem while traveling. Your grandchild or another family member supposedly needs money immediately.
And then comes an important instruction:
"Please don't tell Mom and Dad."
Family emergency scams have existed for years, but technology is making them more convincing.
A Familiar-Sounding Voice Isn't Proof
Scammers may gather information about families from social media, public records and other online sources.
Artificial intelligence has added another concern. Voice-cloning technology can potentially be used to imitate someone's voice from a relatively small audio sample.
That means hearing what sounds like your grandchild, child or another person you know should no longer be considered proof by itself that you're actually speaking with that person.
The scammer may know names and family relationships. They may know where someone attends school, where they recently traveled or other information that makes the story sound believable.
Then Someone "Official" May Take Over
The first caller may quickly hand the telephone to someone claiming to be:
-
A police officer.
-
An attorney.
-
A bail-bond representative.
-
A doctor or hospital employee.
-
A court official.
That second person makes the emergency seem more legitimate.
You may be told that money is needed immediately for bail, legal fees, medical expenses or another emergency.
The caller may request cash, gift cards, cryptocurrency, a wire transfer or another difficult-to-reverse form of payment.
Stop and Verify the Emergency Yourself
If someone claims that a family member is in trouble, you don't need to resolve the situation during that telephone call.
Hang up.
Call your family member directly using the telephone number you already have for them.
If you can't reach them, call their parent, spouse, sibling or another family member who can independently verify what is happening.
Don't use a telephone number provided by the caller.
Consider a Family Verification Question
Families may also want to establish a simple question or family password that can be used when something doesn't seem right.
Choose something a stranger wouldn't easily discover from social media.
But don't rely exclusively on a password. If circumstances allow, ending the call and independently contacting the family member remains one of the safest ways to verify an emergency.
Secrecy Is a Major Warning Sign
One of the strongest warning signs is being told:
"Don't tell anyone."
A scammer doesn't want you talking with another family member because another person may immediately recognize that something isn't right.
A genuine family emergency can withstand a few minutes of verification.
Concern for someone you love is exactly why you should verify before sending money.
Email, Text, Package Delivery & Phishing Scams
Not every scam begins with a telephone call.
An email or text message may tell you:
"Your package could not be delivered."
"You have an unpaid toll."
"Your account has been suspended."
"Your payment method needs to be updated."
"Click here to review this document."
"Unusual activity was detected. Verify your account immediately."
The message may appear to come from a delivery company, bank, government agency, streaming service, utility company or business you regularly use.
The objective is usually to get you to click before you stop to think.
What Is Phishing?
Phishing is an attempt to trick you into providing information or taking an action by pretending to be someone or something you trust.
A link may take you to a website designed to look almost identical to the real company's website.
You enter your username and password.
The website doesn't belong to the company.
You've just given your login information to the scammer.
Other messages may attempt to obtain credit-card information, Social Security numbers or other personal information, or may try to install malicious software on your device.
Package Delivery Messages Deserve Extra Caution
Package scams are particularly effective because so many of us regularly receive deliveries.
A text may claim that a package couldn't be delivered because of an incomplete address or unpaid fee.
The amount requested may be very small.
That's intentional.
You may think:
"It's only 30 cents or a couple of dollars. I'll just take care of it."
But the small delivery charge may simply be a way to get your credit-card information or other personal information.
If you're expecting a package, don't use the link in an unexpected message.
Instead, open the delivery company's app or independently visit the company's official website and enter your tracking information there.
Look Carefully — But Don't Depend on Appearance Alone
Traditional advice often tells people to look for spelling mistakes, poor grammar or an unusual-looking logo.
Those can still be warning signs.
But they aren't enough anymore.
Modern scam messages can be professionally written and visually convincing. Artificial intelligence has made it easier to create polished emails and messages without the obvious spelling and grammatical mistakes people once associated with scams.
A message that looks professional can still be fraudulent.
Be Careful With QR Codes, Too
A QR code is simply another way of directing you to a website.
Don't assume a QR code in an unexpected email, text, letter or invoice is safe because you aren't clicking a traditional link.
Ask yourself the same question:
Was I expecting this, and can I independently verify where I need to go?
Unexpected Attachments Can Also Be Dangerous
Be cautious about opening unexpected attachments, even when the message appears to come from someone you recognize.
A compromised email account can be used to send messages that appear to come from a legitimate contact.
If something seems unusual, contact the person separately before opening the attachment.
Don't Let the Message Choose How You Verify It
This principle applies to almost every scam discussed in this resource.
If an email says there is a problem with your bank account, don't use the email's link to check your bank.
If a text says your package couldn't be delivered, don't use the text's link to check the shipment.
If a message says your account has been compromised, don't call the telephone number supplied in the message.
Go around the message.
Open the app yourself. Type the website address yourself. Call a telephone number you already know or independently verify.
That simple habit breaks one of the scammer's most important tools — controlling how you respond.
Before You Click, Ask Three Questions
Was I expecting this message?
Is the message trying to make me act quickly?
Can I verify this another way without using the link, telephone number or QR code they provided?
If you're uncertain, don't click.
Stop. Slow Down. Verify. Talk to Someone.
Romance, Friendship & Relationship Scams
Not every scam begins with a threat or an emergency.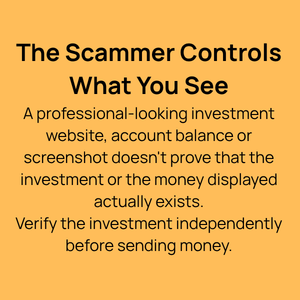
Some begin with a conversation.
A friendly message appears on social media. Someone responds to something you posted. A person reaches out through a dating site. You begin communicating regularly, and over time a relationship develops.
The person seems interested in your life. They listen. They remember details. They may communicate with you every day.
Weeks or even months can pass before money is ever mentioned.
That's what can make romance and friendship scams so difficult to recognize.
The Relationship May Be the Setup
A scammer may claim to live or work somewhere that makes meeting in person difficult.
They may say they are:
-
Working overseas.
-
Serving in the military.
-
Traveling extensively for business.
-
Working on an offshore project.
-
Temporarily caring for a family member.
-
Planning to visit you soon.
There always seems to be a reasonable explanation for why you haven't met face-to-face.
Meanwhile, the relationship becomes increasingly personal.
Eventually, something changes.
The First Request May Seem Reasonable
There may be a medical emergency.
A travel problem.
A business setback.
A family member who needs help.
A problem accessing money while overseas.
Or the person may not ask for money at all.
Instead, they may tell you about an investment that has been extremely successful for them and offer to show you how to participate.
That's an increasingly important warning sign.
Romance Scams and Investment Scams Can Overlap
A person you've met online may casually begin talking about cryptocurrency, stocks, foreign currency or another investment.
They may show you screenshots demonstrating how much money they're supposedly making.
They aren't asking you to give them money.
They're helping you make money.
At least that's how it appears.
You may be directed to an investment website or app that looks professional and shows your account increasing in value.
But the website, account balance and profits may all be fake.
The relationship was simply the path used to gain your trust.
Warning Signs to Watch For
Be especially cautious when an online relationship includes:
-
Repeated excuses for why you cannot meet in person.
-
Requests for money, gift cards or cryptocurrency.
-
Requests to receive or transfer money for someone else.
-
Sudden emergencies requiring financial assistance.
-
Pressure to keep the relationship or financial situation private.
-
An offer to teach you how to invest.
-
Recommendations for a particular cryptocurrency platform, investment website or financial adviser.
-
Requests to move conversations away from the original social-media or dating platform.
Don't Let Embarrassment Keep You From Talking to Someone
People who conduct these scams can be extremely patient and skilled at building trust.
If you're concerned about an online relationship, talk privately with someone you trust before sending money or making an investment.
And if you've already sent money, don't allow embarrassment to prevent you from asking for help.
The important question isn't:
"How could I have believed this?"
The important question is:
"What should I do now to protect myself?"
A genuine friend or romantic partner won't object to you taking reasonable steps to protect your financial security.
Trust should never require secrecy, financial pressure or an investment you don't fully understand.
Investment & Cryptocurrency Scams
Investment scams deserve special attention because the potential losses can be enormous.
The opportunity may involve cryptocurrency, stocks, precious metals, foreign currency, real estate or another supposedly exclusive investment.
The pitch can arrive through social media, an online advertisement, a text message, an investment group or someone you've developed a relationship with online.
The details vary, but the message is often similar:
"I've been making excellent returns."
"I can show you how to do it."
"There's very little risk."
"You need to act before this opportunity is gone."
Investment Scams Are Producing Enormous Losses
The Federal Trade Commission reported more than $7.9 billion in reported investment-scam losses during 2025, with a median individual reported loss of more than $10,000.
For older adults, investment scams have also been among the most financially damaging forms of fraud.
That makes any unexpected investment opportunity worth slowing down and independently investigating.
The Investment Account May Look Completely Real
One of the most troubling aspects of modern investment scams is that victims may be given access to an impressive-looking website or app.
You deposit $1,000.
Your account soon shows $1,150.
Then $1,400.
You may even be allowed to withdraw a small amount of money.
Everything appears to be working.
That apparent success encourages you to invest more.
But the numbers displayed on the screen may have nothing to do with a real investment.
The scammer controls what you see.
The Problem Often Appears When You Try to Withdraw Your Money
After you've invested a larger amount, you decide to withdraw some of your profits.
Suddenly there's a problem.
You're told you must first pay:
-
A tax.
-
A processing fee.
-
An account verification fee.
-
An insurance charge.
-
A commission.
-
A security deposit.
-
Another investment requirement.
Paying the additional money doesn't unlock the account.
It simply produces another request for money.
Cryptocurrency ATMs Are Not Government or Bank Payment Machines
Another warning sign is being instructed to withdraw cash and deposit it into a Bitcoin or cryptocurrency ATM.
A scammer may remain on the telephone and provide a QR code or instructions telling you exactly where to send the cryptocurrency.
Stop.
A legitimate government agency, bank or law-enforcement organization will not tell you to protect your money by depositing cash into a cryptocurrency ATM.
Once cryptocurrency is transferred to a scammer, recovering it can be extremely difficult.
Guaranteed Returns Are a Warning Sign
Every legitimate investment involves some degree of risk.
Be suspicious of anyone promising:
-
Guaranteed profits.
-
unusually high returns with little or no risk.
-
A secret investment strategy.
-
An exclusive opportunity available only for a short time.
-
An investment that you shouldn't discuss with your financial adviser or family.
-
A special cryptocurrency platform they will help you use.
The more someone pressures you to make a financial decision quickly, the more important it is to slow the process down.
Verify the Person — And the Investment
Before transferring substantial money into an unfamiliar investment, independently investigate both the investment and the person recommending it.
Don't rely solely on:
-
The website they provide.
-
Testimonials shown on that website.
-
Screenshots of supposed investment returns.
-
Members of an online investment group.
-
Someone you've met through social media.
-
A celebrity endorsement or online video.
Those things can be fabricated.
If you're considering a significant investment, discussing it first with an independent financial professional, attorney or another trusted adviser can provide an additional layer of protection.
Be Careful of the Second Scam
Unfortunately, victims of investment fraud can sometimes be targeted again.
Someone may contact you claiming they can recover the money you lost — for an upfront fee.
They may claim to be an investigator, attorney, government representative or asset-recovery specialist.
Before paying anyone who unexpectedly offers to recover stolen money, independently verify who they are.
Losing money once doesn't mean you should have to lose it twice.
Remember the Basic Rule
An investment opportunity should withstand questions, independent research and time for you to think.
If someone doesn't want you doing those things, don't let their urgency determine what happens to your savings.
Stop. Slow Down. Verify. Talk to Someone.
Home Repair, Contractor & Homeowner Scams
Owning a home creates another opportunity for scammers — particularly when repairs are needed quickly.
Someone knocks on the door and says they noticed damage to your roof.
A contractor says they have materials left over from another job and can give you a special price today.
Someone offers to seal your driveway, trim trees, repair your chimney or handle storm damage.
The work may actually be needed.
The person offering to do it may not be legitimate.
Be Especially Careful After a Storm
Severe weather can bring legitimate contractors into an area — but it can also attract people looking for homeowners who feel pressured to make quick decisions.
Someone may tell you:
"Your roof is badly damaged."
"Your insurance will pay for everything."
"We're already working on several homes in the neighborhood."
"I can give you this price, but only if you sign today."
Don't let an unexpected visitor create an artificial deadline.
A legitimate repair can usually wait long enough for you to verify the contractor and understand what you're agreeing to.
Warning Signs With Home Repair Offers
Be cautious when someone:
-
Appears unexpectedly and pressures you to make an immediate decision.
-
Requests a large cash payment before work begins.
-
Wants the entire project paid in advance.
-
Offers an unusually low price because they have "leftover materials."
-
Is unwilling to provide a written estimate or contract.
-
Can't provide verifiable business information.
-
Pressures you to sign insurance documents you don't understand.
-
Asks you to sign over an insurance payment.
-
Discourages you from obtaining another estimate.
-
Offers to drive you to the bank to withdraw money.
Verify Before You Hire
Before agreeing to substantial home repairs, take some time to investigate.
Ask for the contractor's full business name, address, telephone number and applicable licensing information.
Obtain a written description of the work, materials, price and payment schedule.
For a significant project, consider obtaining more than one estimate.
Check references and independently research the company rather than relying solely on reviews or references supplied by the person standing at your door.
And don't assume someone is trustworthy simply because they say they worked for one of your neighbors.
Verify it.
Be Careful With Utility Impersonators
Someone may also appear at your door claiming to represent a utility company, energy supplier, cable provider or another service.
They may ask to see your utility bill, inspect equipment or collect an overdue payment.
Don't feel obligated to let an unexpected person into your home.
Ask for identification and independently contact the company using a telephone number from your bill or the company's official website.
If someone claims your service will be shut off immediately unless you pay them, stop and verify the situation directly with the utility company.
Property and Deed Solicitations Can Look Official
Homeowners may receive official-looking letters concerning their deed, property records, mortgage, taxes or other public information.
Some are legitimate notices.
Others are advertisements selling a service you may not need or offering documents you can obtain elsewhere for little or no cost.
The fact that a letter contains your name, property address, mortgage information or other accurate details doesn't necessarily mean it came from a government agency.
Much of that information may be available through public records.
Read the fine print and independently verify who sent the notice before sending money or providing additional information.
When Someone Comes to Your Door, You Control the Timeline
You don't owe an unexpected salesperson or contractor an immediate decision.
It's perfectly reasonable to say:
"Thank you. I'll look into it and contact you if I'm interested."
Then close the door and investigate independently.
A legitimate business opportunity should still be legitimate tomorrow.
Scams During Major Life Transitions
There are times in life when we're simply managing more than usual.
A spouse has died.
You're settling an estate.
You're preparing a longtime home for sale.
You're downsizing.
You're considering independent living or another housing option.
You're handling financial accounts or household responsibilities that someone else may have managed for years.
These transitions can involve dozens of unfamiliar decisions, telephone calls, emails, documents, contractors and financial transactions.
Unfortunately, that can also create opportunities for scammers.
A Life Transition Can Temporarily Change Your Routine
Consider what happens after the death of a spouse.
The surviving spouse may suddenly be responsible for bills, online accounts, insurance policies, investments, home repairs or financial decisions that the other spouse traditionally handled.
Or consider an adult child helping a parent prepare a home after 40 or 50 years.
There may be contractors, movers, estate-sale companies, charitable donations, financial accounts, legal documents and unfamiliar people coming and going.
Nothing about that means the person is incapable of making good decisions.
It simply means there are more decisions, more unfamiliar contacts and more opportunities for something questionable to slip through.
Probate and Estate Administration Can Attract Unwanted Attention
Deaths, property ownership and probate proceedings can involve information that is publicly available.
That means a family may receive unexpected letters, telephone calls or offers from people who already know:
-
The name of the person who died.
-
The property address.
-
The name of a Personal Representative or family member.
-
Information concerning the estate or property.
Knowing those details doesn't mean the person contacting you is connected with the court, your attorney or another trusted professional.
Treat unexpected contacts involving estate property, money or personal information with the same caution you would any other unsolicited communication.
Selling a Longtime Home Creates New Contacts
Preparing a home for sale can introduce homeowners to people they haven't previously worked with:
Contractors.
Movers.
Clean-out companies.
Estate-sale professionals.
Repair companies.
Inspectors.
Real estate professionals.
Title and closing companies.
That makes independent verification particularly important.
Whenever possible, know who you're dealing with, why they're involved, and who referred them.
If someone unexpectedly contacts you claiming to be connected with your real estate transaction, attorney, title company or another professional, don't automatically assume the request is legitimate simply because they know details about the transaction.
Be Extremely Careful With Wiring Instructions
Real estate transactions can involve significant amounts of money, making them attractive targets for criminals.
Fraudulent emails can be designed to look as though they came from a real estate professional, title company, attorney or other legitimate party.
The message may provide new or revised instructions for wiring money.
Never rely solely on emailed wiring instructions or an unexpected change in payment instructions.
Before sending money, independently verify the instructions with the appropriate title company, financial institution, attorney or other responsible professional using a telephone number you already know or independently obtain.
A last-minute change involving where money should be sent deserves immediate verification.
Downsizing Can Create Another Type of Vulnerability
When someone is preparing to leave a longtime home, possessions may be sold, donated, discarded or distributed among family members.
It's easy to focus on furniture and household items and overlook what those items may contain.
Before disposing of desks, filing cabinets, old computers, phones, tablets or boxes of paperwork, look for:
-
Tax returns.
-
Bank and investment statements.
-
Social Security information.
-
Medical or insurance records.
-
Checkbooks.
-
Credit-card statements.
-
Password lists.
-
Old computers and digital storage devices.
-
Documents containing account numbers or other personal information.
Sensitive documents should be securely destroyed rather than simply placed in the trash.
Electronic devices should also be properly erased before being sold, donated or recycled.
Families Can Create a Simple Safety Net
One of the best protections doesn't require sophisticated technology.
Create an understanding within the family:
Before Mom, Dad or another family member sends a substantial amount of money because of an unexpected telephone call, email or text, someone else gets a call first.
This isn't about taking away someone's independence.
It's about providing a second set of eyes when something unusual happens.
The same rule can work for all of us.
If I'm confronted with an unexpected financial request that doesn't seem right, there's nothing wrong with stopping and asking someone else what they think.
Slow Down During a Transition
Major life transitions already come with enough pressure.
An unexpected caller, contractor, email or financial request shouldn't be allowed to create more.
When something involves your home, savings or personal information, give yourself permission to say:
"I'm not making that decision right now. I'm going to verify this first."
Then do exactly that.
Stop. Slow Down. Verify. Talk to Someone.
Planning a move for yourself or helping an aging parent?
Major housing transitions involve many moving pieces. Having a plan—and knowing who is involved—can make the process easier and safer.
What to Do If You Think You've Been Scammed
Sometimes you don't realize something was a scam until after you've responded.
Maybe you clicked a link.
You gave someone a verification code.
You provided credit-card or banking information.
You allowed someone access to your computer.
You purchased gift cards, transferred money or sent cryptocurrency.
Or perhaps something simply doesn't feel right after you've had time to think about the conversation.
Act quickly.
The sooner you respond, the better the opportunity may be to protect your accounts, stop additional losses and preserve information that could be useful when reporting the fraud.
1. Stop Communicating With the Person
End the telephone call, text conversation, email exchange or online communication.
Don't send additional money — even if the person says one more payment will solve the problem, release your funds, pay a tax or recover money you've already lost.
Don't threaten or argue with the scammer.
Simply stop communicating.
2. Contact Your Bank or Financial Institution Immediately
If money or financial information was involved, contact your bank, credit union, credit-card company or investment firm as quickly as possible.
Use a telephone number you independently verify.
Explain exactly what happened.
Ask whether a transaction can be stopped, reversed or recalled and whether accounts or cards should be frozen, closed or replaced.
Even when you're unsure whether money was actually taken, let the financial institution know that your account information may have been compromised.
3. If You Paid With a Gift Card, Contact the Gift Card Company
Keep the gift card and receipt if you still have them.
Contact the company that issued the card and explain that it was used in a scam.
Do this as quickly as possible.
Never send photographs of gift cards, receipts or the numbers on the back of a card to someone who unexpectedly contacts you.
4. If Someone Accessed Your Computer, Disconnect It
If you gave someone remote access to your computer, disconnect the device from the internet and end the remote-access session if possible.
Don't continue banking, shopping or accessing sensitive accounts from that computer until you're confident it is secure.
Consider having the device inspected by a reputable computer professional.
If you signed into financial accounts while someone had remote access, tell your financial institutions what happened.
5. Change Compromised Passwords
If you provided a password or believe someone may have obtained it, change it.
Start with particularly important accounts such as:
-
Email.
-
Banking and investments.
-
Credit cards.
-
Apple, Google or Microsoft accounts.
-
Social media.
-
Shopping accounts.
If you've used the same password on multiple websites, change it everywhere it was used.
Whenever available, consider enabling multi-factor authentication for additional protection.
6. Preserve the Evidence
Don't immediately delete everything.
Save:
-
Emails.
-
Text messages.
-
Telephone numbers.
-
Screenshots.
-
Website addresses.
-
Receipts.
-
Gift-card information.
-
Bank-transfer information.
-
Cryptocurrency transaction information.
-
Names used by the people who contacted you.
-
Dates and approximate times of conversations.
Write down what happened while the details are still fresh.
This information may be helpful to your bank, law enforcement or agencies investigating the fraud.
7. Monitor Your Financial Accounts and Credit
Watch bank, credit-card and investment accounts closely for unfamiliar transactions.
If sensitive personal information was compromised, you may also want to review your credit reports and consider placing a fraud alert or credit freeze with the major credit bureaus.
A credit freeze can make it more difficult for someone to open a new credit account using your identity.
8. Report the Scam
Reporting fraud can help investigators identify patterns and may help protect other people from experiencing the same thing.
You can report scams and fraud to the Federal Trade Commission at ReportFraud.ftc.gov.
Internet-related fraud can be reported to the FBI Internet Crime Complaint Center at IC3.gov.
Older adults and family members can also contact the National Elder Fraud Hotline at 833-FRAUD-11 (833-372-8311) for assistance.
Depending on what occurred, you may also want to contact your local law-enforcement agency.
9. Watch for Recovery Scams
After someone loses money to a scam, another person may appear offering to recover it.
They might claim to be an attorney, investigator, government representative or recovery specialist.
Then they ask for an upfront fee.
Stop.
It may be another scam.
Never assume someone is legitimate simply because they know details about the original fraud.
Most Important: Tell Someone
Don't let embarrassment or fear keep you from asking for help.
Scammers deliberately create situations designed to make people act before they have time to think.
If you realize afterward that something may have gone wrong, tell someone you trust and begin taking action.
The priority isn't assigning blame. The priority is limiting the damage and protecting what happens next.
How Adult Children and Families Can Help Protect an Older Parent
Adult children often ask how they can protect a parent from scams.
The answer isn't simply:
"Tell Mom or Dad not to answer the telephone."
Scams change too quickly, and many legitimate parts of everyday life now involve telephone calls, email, text messages and online accounts.
A better approach is to create a family system for handling something unusual.
Start the Conversation Before Something Happens
Don't wait until there's been a financial loss.
Have a simple conversation with your parents about the scams you're seeing.
You might say:
"I'm getting some incredibly convincing scam calls and emails lately. If either of us gets something unusual involving money, let's agree to check with each other before doing anything."
Notice the difference.
You're not saying:
"I'm worried you're going to get scammed."
You're saying:
"They're coming after all of us. Let's watch out for each other."
That preserves independence while creating another layer of protection.
Establish a Family "Call First" Rule
Consider a simple family agreement:
Before responding to an unexpected request involving a substantial amount of money, call another family member or trusted person first.
The amount isn't as important as establishing the habit.
The rule might apply whenever someone unexpectedly asks you to:
-
Transfer money.
-
Withdraw a large amount of cash.
-
Purchase gift cards.
-
Send cryptocurrency.
-
Provide banking information.
-
Change where money is being sent.
-
Allow remote access to a computer.
-
Make an unfamiliar investment.
-
Keep a financial transaction secret.
One additional telephone call can interrupt the pressure the scammer is trying to create.
Create a Family Verification Plan
Families may want to decide in advance how they'll verify a genuine emergency.
Keep important family telephone numbers readily available.
Consider establishing a family password or question that wouldn't be easily discovered through social media.
And make sure everyone understands the basic rule:
If someone says a family member is in trouble, independently contact that family member or another relative before sending money.
Talk About Secrecy
Make one thing particularly clear:
A request to keep a financial transaction secret is a reason to tell someone.
Scammers may tell a victim that bank employees can't be trusted, family members will interfere, or law enforcement has ordered them not to discuss the situation.
That's exactly when another person needs to become involved.
Know Who Your Parents Normally Work With
It can help for adult children to know the names of the professionals their parents already trust, when their parents are comfortable sharing that information.
That might include:
-
Banker or financial adviser.
-
Attorney.
-
Insurance professional.
-
Accountant.
-
Real estate professional.
-
Trusted home-repair professionals.
-
Computer or technology support person.
When an unfamiliar person suddenly appears claiming to be connected with one of these areas, there's someone established who can help verify the situation.
Pay Attention During Major Life Changes
A little additional communication can be especially valuable after:
-
The death of a spouse.
-
A serious change in family circumstances.
-
A move from a longtime home.
-
Downsizing.
-
Estate or probate administration.
-
A transition to independent or assisted living.
-
A period involving substantial home repairs.
-
A major real estate or financial transaction.
These situations can generate legitimate unfamiliar telephone calls, emails, bills and paperwork.
That makes independent verification even more important.
Technology Can Help — But It Isn't the Entire Answer
Spam filters, call-screening services, strong passwords, multi-factor authentication and credit monitoring can all provide additional protection.
But technology can't replace communication.
One of the strongest protections may simply be knowing:
"If something doesn't seem right, I have someone I can call."
Protect Independence While Providing Support
Helping an older parent doesn't necessarily mean taking over their finances or making decisions for them.
Often, the most useful role an adult child can play is simply being available as a second set of eyes.
Ask questions.
Listen.
Help verify.
And avoid making someone feel foolish if they nearly fell for something.
If Mom or Dad tells you about a suspicious call, a useful response isn't:
"I can't believe you almost did that."
It's:
"I'm glad you called. Let's check it out together."
That makes it much more likely they'll call you again the next time something happens.
Make It a Family Rule
Scammers rely on isolation, urgency and fear.
Families can counter that with communication.
When money, personal information or an unexpected emergency is involved:
Stop. Slow Down. Verify. Talk to Someone.
That rule isn't just for older adults.
It's good advice for all of us.
Where to Report a Scam & Find Trusted Help
If you believe you or someone you know has encountered a scam, reporting it can be important — even if no money was lost.
Reports help government agencies and law enforcement identify patterns, investigate criminal activity and warn others about emerging scams.
If money has already been sent or financial information has been compromised, contact the appropriate bank, credit-card company or financial institution first. Acting quickly may provide the best opportunity to stop or limit additional losses.
Federal Trade Commission — ReportFraud.gov
The Federal Trade Commission collects reports about fraud, scams and deceptive business practices.
ReportFraud.ftc.gov
The FTC also maintains consumer information about current scams and steps you can take if you've been affected.
Consumer.ftc.gov
FBI Internet Crime Complaint Center — IC3
Internet-related crimes and scams can be reported to the FBI's Internet Crime Complaint Center.
IC3.gov
Reports can include phishing, investment fraud, cryptocurrency scams, tech-support fraud, business email compromise and other internet-enabled crimes.
If you've experienced an internet-related financial loss, preserve as much information as possible about the transaction before submitting your report.
National Elder Fraud Hotline
Older adults and family members who need assistance after suspected fraud can contact the National Elder Fraud Hotline.
833-FRAUD-11
833-372-8311
The hotline is operated through the U.S. Department of Justice's Office for Victims of Crime and can help older adults understand available reporting and support options.
IdentityTheft.gov
If someone has obtained or used your personal information, the Federal Trade Commission provides a separate resource for identity theft.
IdentityTheft.gov
The site can help you develop a recovery plan based on the type of information that was compromised.
Your Financial Institution
If money, credit cards, checks, bank accounts or investment accounts are involved, contact the appropriate financial institution immediately.
Use a telephone number you independently verify — such as the number printed on the back of your credit or debit card or on an account statement.
Tell them you believe fraud may have occurred and ask what immediate steps they recommend.
Local Law Enforcement
Depending upon what occurred, you may also want to contact your local police department or sheriff's office.
If someone is at your home, you feel physically threatened, or you believe there is an immediate danger, call 911.
Keep These Resources Somewhere Accessible
Consider saving these resources with other important household and financial information.
You might also print this section for a parent or family member who doesn't regularly search for information online.
And remember:
Don't use contact information provided by the person you suspect may be scamming you.
Independently locate the organization and make the call yourself.
A Final Thought: When Something Doesn't Feel Right, Stop
Scams will continue to change.
The telephone number will change. The email will look different. The company being impersonated will change. New technology will make some scams even more difficult to recognize.
That's why trying to memorize every possible scam isn't the answer.
Developing a habit of verification is.
Throughout my years working with homeowners, seniors and families in Greater Lansing, I've learned the importance of slowing down when a major decision doesn't feel right.
That applies to housing decisions, financial decisions — and certainly to unexpected requests for money or personal information.
You don't have to make a decision simply because someone else tells you it's urgent.
You don't have to stay on the telephone.
You don't have to click the link.
And you don't have to figure everything out by yourself.
Remember the 60-Second Scam Rule
STOP
Don't send money, provide sensitive information or give someone access to your computer.
SLOW DOWN
Don't allow fear or urgency to make the decision for you.
VERIFY
End the conversation and independently verify what you've been told.
TALK TO SOMEONE
A family member, friend or trusted professional can provide another perspective before you act.
Helping Greater Lansing Seniors and Families Plan Ahead
Many of the families I work with are navigating more than a real estate transaction.
They may be helping aging parents, downsizing from a longtime home, settling an estate or simply beginning to think about what the next several years might look like.
Those decisions deserve time, good information and a thoughtful plan.
If you're beginning one of those conversations, I've developed additional Greater Lansing resources to help you understand your options and decide what makes sense for you and your family.
Explore the Senior Transition Resource Center
Helping Parents Move: Resources for Adult Children & Families
There is no obligation to make a move simply because you're gathering information.
Sometimes the best first step is simply understanding your options.
Frequently Asked Questions About Scams Targeting Seniors
What are some of the most common scams targeting seniors?
Common scams include government and jury-duty impersonation, fake Amazon or Apple purchase alerts, bank and credit-card fraud calls, tech-support scams, grandchild and family-emergency scams, phishing emails and texts, romance scams, investment and cryptocurrency fraud, and home-repair scams.
The specific story may change, but many scams use the same techniques: creating fear or urgency, discouraging you from talking with someone else, and pressuring you to send money or provide personal information before you have time to verify what is happening.
How can I tell if a jury-duty or government call is a scam?
Be suspicious of an unexpected caller who threatens arrest or other immediate consequences unless you make a payment.
Government agencies and law-enforcement organizations will not demand that you resolve a problem by purchasing gift cards, sending cryptocurrency or moving money to a special account.
If you're concerned that a call might be legitimate, hang up and independently find the official telephone number for the court, police department, sheriff's office or government agency. Don't use a telephone number supplied by the caller.
Will my bank ever ask me to move money to protect it from fraud?
If someone unexpectedly contacts you and says your money is at risk and must be transferred to a "safe," "secure" or "protected" account, stop.
Don't transfer the money.
Hang up and contact your bank yourself using the telephone number printed on the back of your debit or credit card, an account statement or the bank's official app or website.
Never rely solely on Caller ID to determine whether a call is really coming from your bank.
What should I do if I gave a scammer my banking or credit-card information?
Contact your bank, credit union or credit-card company immediately using a telephone number you independently verify.
Explain what happened and ask whether accounts or cards should be frozen, closed or replaced and whether any transactions can be stopped or reversed.
Change potentially compromised passwords and closely monitor your accounts for unfamiliar activity. If personal identifying information was compromised, you may also want to review your credit reports and consider a fraud alert or credit freeze.
Can scammers imitate the voice of my child or grandchild?
Technology can be used to create convincing imitations of someone's voice, so hearing what sounds like a family member should not be your only method of verification.
If someone calls claiming that a child, grandchild or other family member is in an emergency and needs money, hang up and independently contact that family member or another relative.
Families may also want to establish a private family verification word or question that isn't easily discovered through social media.
What should I do if I gave someone remote access to my computer?
End the remote-access session and disconnect the computer from the internet.
If you entered banking, investment, credit-card or other sensitive information while the person had access, contact those financial institutions immediately from another trusted device.
Change potentially compromised passwords and consider having the computer inspected by a reputable technology professional before using it again for sensitive financial activity.
Where can seniors report a scam or fraud?
Fraud can be reported to the Federal Trade Commission at ReportFraud.ftc.gov.
Internet-related crimes can be reported to the FBI's Internet Crime Complaint Center at IC3.gov.
Older adults and their families can also contact the National Elder Fraud Hotline at 833-FRAUD-11 (833-372-8311).
If money was sent, contact the bank, credit-card company or other financial institution involved as quickly as possible. If there is an immediate physical threat or emergency, call 911.
How can adult children help protect aging parents from scams without taking away their independence?
Start the conversation before a scam occurs.
Instead of approaching the subject as something only older adults need to worry about, make scam prevention a family practice.
Consider establishing a simple rule: before anyone sends a substantial amount of money, provides sensitive financial information or responds to an unexpected emergency request, they contact another trusted person first.
Most importantly, make it easy for a parent to ask for help without feeling embarrassed or judged.
A simple family response can be:
"I'm glad you called. Let's verify it together."
That creates a second set of eyes while respecting the older adult's independence.
Remember: Stop. Slow Down. Verify. Talk to Someone.
Explore the Senior Transition Resource Center
Helping Parents Move: Resources for Adult Children & Families
Important Note
This resource is provided for general educational and informational purposes. Scam techniques change frequently, and no article can identify every form of fraud.
This information is not intended as legal, financial, cybersecurity or law-enforcement advice. If you believe you've experienced fraud or identity theft, contact the appropriate financial institution, government agency, law-enforcement organization, attorney or other qualified professional based on your circumstances.
Mike Bowler SRES, CRB, ePRO
eXp Realty LLC
517-755-8168
6639 Centurion Dr. Lansing, MI
Mike@MikeBowler.com
Website: MikeBowler.com
Visit My YouTube Channel
https://bit.ly/eXpRealtyMikeBowler
Founder | Greater Lansing Home Transition Resource Center